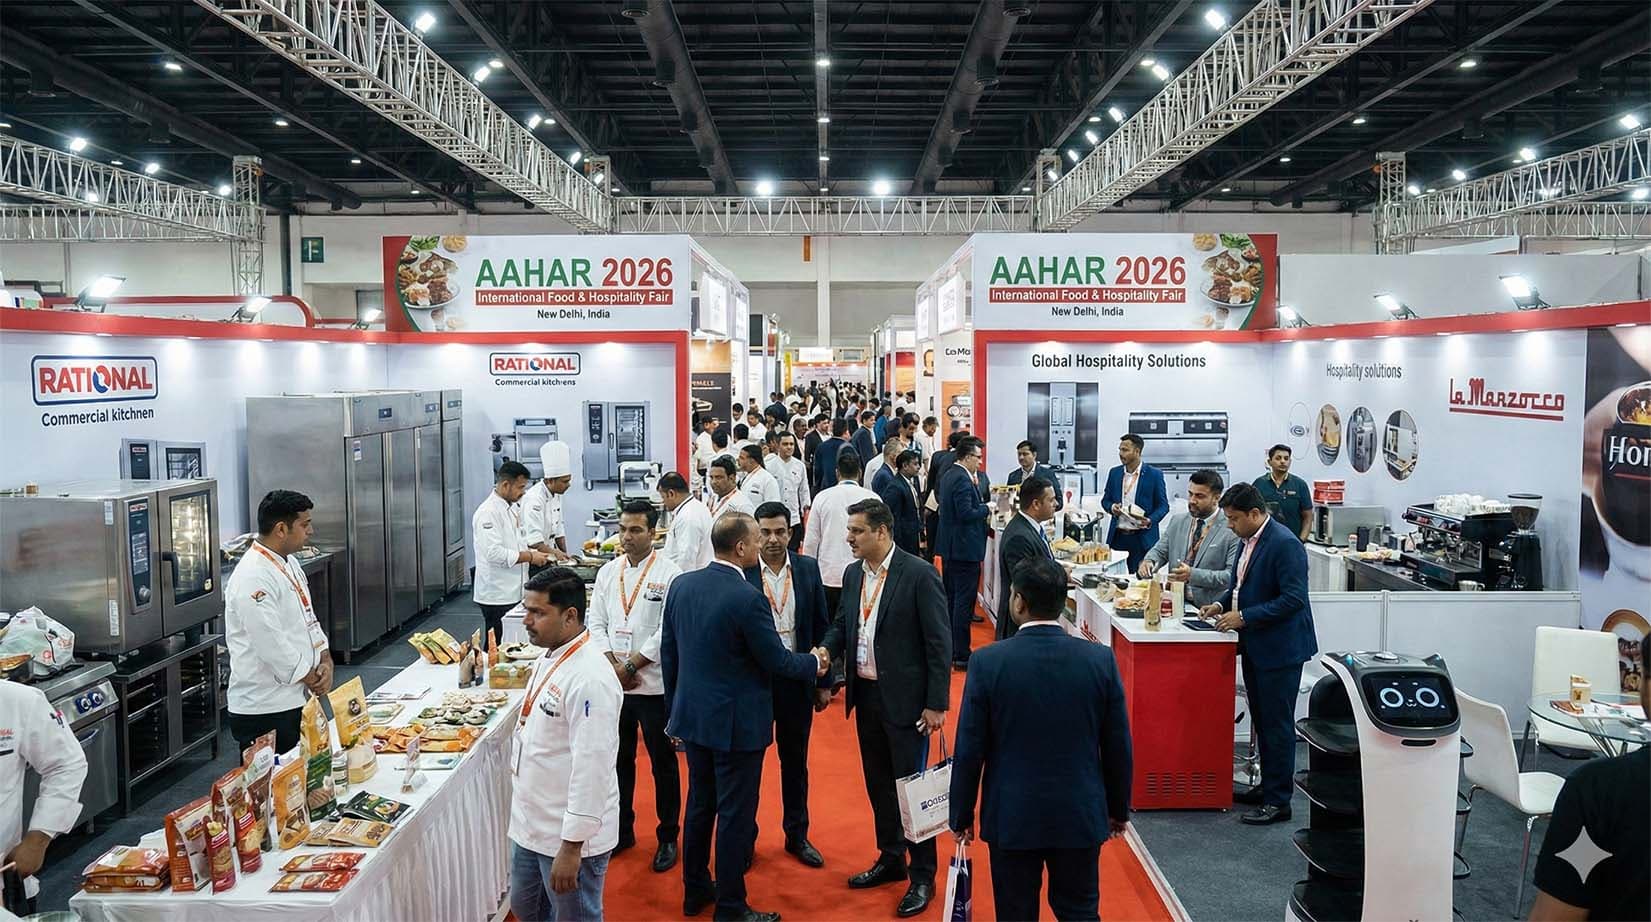
India's hotel story remains one of the most compelling in the world. A large, young population that is travelling more every year, rising domestic incomes, an expanding middle class discovering leisure, a steady stream of business and MICE demand, and infrastructure — airports, highways, expressways — opening up markets that were unreachable a decade ago. The structural case for building and owning hotels in India is genuinely strong, and it is not going away.
But a strong structural story is not the same as an easy one. As we move through the second half of 2026, the investment picture rewards discipline far more than enthusiasm. The markets that looked under-supplied a few years ago have attracted a wave of new development; capital and construction costs are not what they were; and the gap between a well-conceived project and a poorly-conceived one has widened. This is a market for owners who do their homework, not for those betting on a rising tide to lift every hotel. Here is how to read it.
The demand story is real — and uneven
Domestic travel continues to be the engine, and it runs deeper and broader than international demand, insulating Indian hotels from the global swings that hurt more tourism-dependent markets. Weddings, religious and spiritual tourism, business travel, and a growing leisure habit all feed it. But the demand is uneven across markets and segments. A tier-two city on a new expressway with real corporate and wedding demand is a very different proposition from a saturated metro micro-market where six new hotels are opening at once. The national story is bullish; your specific market may not be.
Supply is catching up in the hot markets
The flip side of a good demand story is that everyone reads it. Markets that were genuinely under-supplied have drawn a pipeline of new rooms, and in some of them supply is now arriving faster than demand can absorb it. Before committing to a project, the single most important discipline is to underwrite it against both current and announced pipeline supply — because the hotel you build competes with the ones being built alongside it. Judging a bankable site has never depended more on getting the supply picture right.
Costs and capital demand realism
Construction, FF&E, and financing costs have risen, and the era of underwriting a project on optimistic, thin numbers is over. Projects now need honest all-in costing and a capital structure built for how a hotel actually behaves — enough equity, debt sized to stabilised cash flow, and a genuine working-capital buffer. The projects that will struggle in the next few years are the ones financed as though costs and timelines would be kind. Getting the financing structure right matters more in a higher-cost environment, not less.
Segments to watch
Across the market, mid-scale and upper-midscale continue to look like the sweet spot for much of India — strong, broad demand, a manageable operating model, and a rate the market will actually pay. Branded budget and economy hotels have room in under-served corridors. Upscale and luxury remain genuine opportunities in the right metros and leisure destinations but demand a market that truly supports the rate. The recurring lesson is to match the segment to what the market rewards, not to what feels prestigious to own.
The opportunities that stand out
Beyond new-build, several themes look attractive for the disciplined owner: conversions and rebranding of existing assets in strong locations, hotels serving the spiritual and religious tourism circuits that keep expanding, properties positioned around new infrastructure before the market fully prices it in, and the wedding-and-events demand that Indian hotels are uniquely placed to capture. Each rewards local knowledge and careful underwriting over broad optimism.
How an owner should act
The through-line for the rest of 2026 is simple: the structural case for Indian hotels is intact, but the margin for error has shrunk. Underwrite conservatively, understand your specific micro-market and its pipeline, structure capital for the real all-in cost, and choose your segment from the demand rather than from ambition. Owners who do this will find genuine opportunity; those who ride the national story without doing the local work will find the competition did.
Where to start this month
If you are weighing a hotel investment in the current market:
- Underwrite against current and pipeline supply in your specific micro-market.
- Cost the project honestly — all-in, including FF&E, pre-opening, and working capital.
- Match the segment to demand the market actually rewards, not to prestige.
- Structure capital conservatively for a higher-cost, slower-ramp environment.
- Look hard at conversions and infrastructure-led markets, not just new-build in hot spots.
- Get an independent read on the local demand-supply balance before committing.
India's hotel opportunity is real and durable — for owners who bring discipline to it. If you want an objective read on a specific market or project before you commit, book a strategy call.
Owner's guides
Brand selection, pre-opening & feasibility playbooks — download instantly.
Written by
Rachit Goel
Founder & Principal Hospitality Consultant
Founder of The Hotel Adviser and a hospitality leader with 25+ years of hands-on experience across Marriott, Radisson, Ramada and Taj — spanning pre-opening, operations, revenue management and food & beverage.